





Let’s work together to find a solution
Rely on AVANA Capital to help preserve your wealth and create growth for your business.
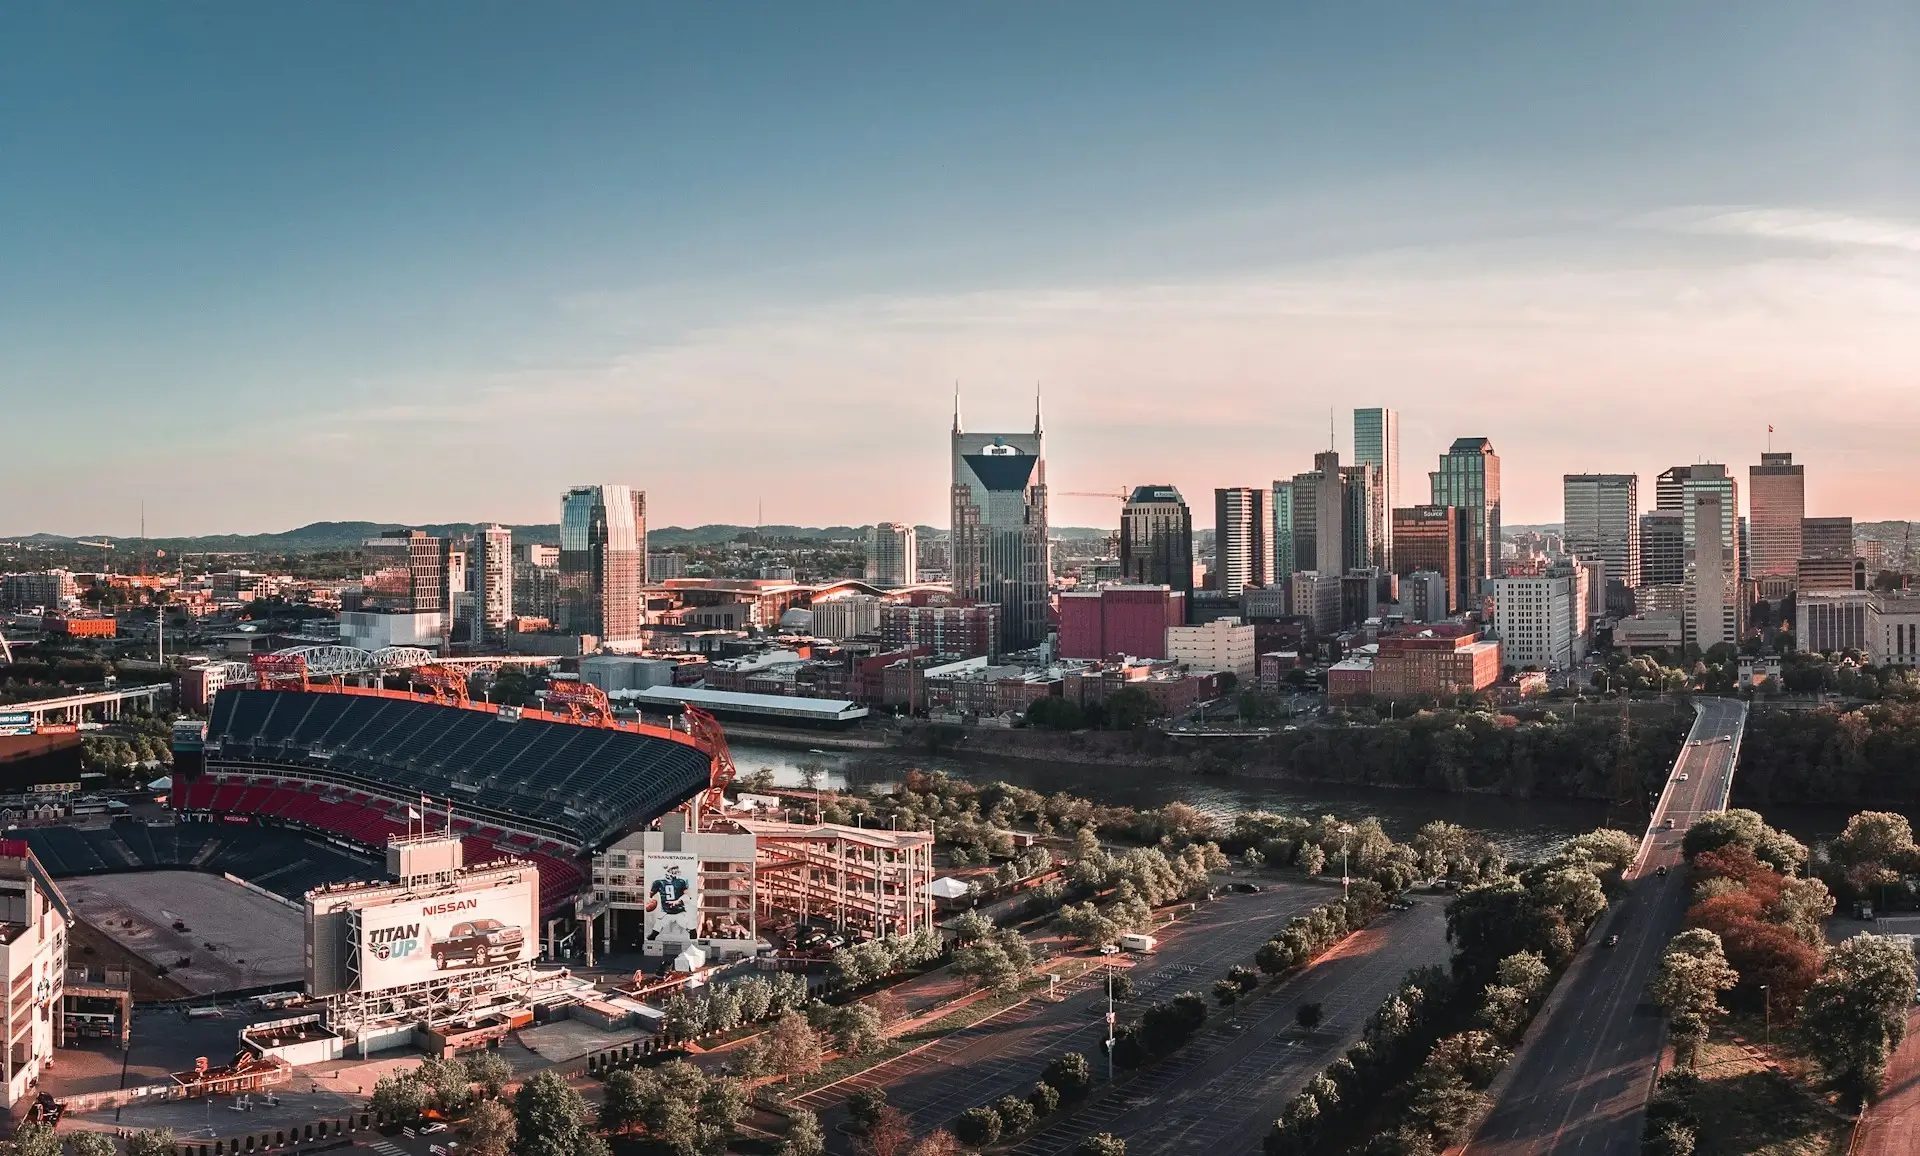
Nashville has one of the deepest commercial construction pipelines in the Southeast, and Memphis moves freight for much of the country. Both produce the same financing need at scale: buildings that are finished but not yet earning, and hotels mid-renovation that will not support permanent debt until the guests come back. Tennessee’s bank consolidation in 2026 pushed the state’s largest commercial lender materially upmarket, which widened the gap for mid-market borrowers exactly where that demand sits.
Searching for the best bridge loan lenders in Tennessee mostly returns residential fix-and-flip lenders. This guide covers commercial bridge financing — hospitality, industrial, retail, multifamily and mixed-use, generally $1 million and up.
You are a homeowner buying before you sell. You need residential or consumer bridge financing from a mortgage lender, bank or credit union. Nothing below applies.
You are flipping houses or buying single-family rentals. Tennessee is well served. Unitas Funding and Ternus lend to Tennessee investors, Capital Fund 1 serves Nashville, and national platforms including Lima One Capital (minimum $75,000) and Easy Street Capital are built for residential investment property.
You own or are buying income-producing Tennessee commercial property — a Nashville hotel carrying a brand-mandated renovation, newly delivered space in lease-up, a Memphis distribution building, a retail centre mid-repositioning — and you need short-term capital until the asset supports permanent debt. This page is for you.
For how the flavours of private capital differ, see our guide to hard money versus private money lenders.
AVANA Capital is a direct commercial real estate lender — not a broker or a marketplace — with $1.7 billion in loans closed over 23+ years and lending coverage in all 50 states. Its bridge program is backed by a joint venture with Oaktree Capital — institutional capital behind the loan.
Two facts make it relevant in post-consolidation Tennessee. Its range of $5 million to $30 million sits precisely in the band that widened — above community-bank comfort, below super-regional priority. And hospitality is its deepest property type, which matters in a state where Nashville’s hotel market is a major share of commercial activity and community banks cap the asset class. There is no footprint, so Chattanooga, Jackson and the Tri-Cities reach the same credit team as Nashville. AVANA-financed projects have supported 5,000+ jobs created in the USA.
Best fit: Tennessee hotel PIP and acquisition bridge, lease-up on newly delivered space, single-tenant industrial, mid-market commercial deals, out-of-state sponsors.
Unitas Funding is a Tennessee hard money lender providing real estate investor loans across the state, ranking consistently in Tennessee hard-money search results.
Best fit: Tennessee investor deals, weighted toward residential and smaller transactions. Confirm current loan ranges and whether commercial income-producing property is in appetite.
Ternus is a private and hard money lender serving Tennessee real estate investors, appearing consistently in state hard-money results with a product set aimed at investor acquisition and renovation.
Best fit: Tennessee investor deals. Verify loan range, leverage and commercial appetite directly — published parameters are thinner than the lenders above.
Founded in 2009 and headquartered in Scottsdale, Arizona, Capital Fund 1 lends on residential and commercial property with a specific commercial bridge product — amounts up to $10,000,000, rates from roughly 7.99% to 11.99%, terms of 6 months to 2 years, often with no prepayment penalty, and funding in 3–5 days. It maintains a Nashville hard-money presence.
Best fit: Tennessee deals up to $10 million needing genuine speed, across residential or commercial property. One of the few national hard-money lenders with a real commercial product.
Lima One Capital is a national residential-investor lender headquartered in Greenville, South Carolina and lending in 46 states. Products are fix-and-flip, 13-month bridge, DSCR rental and portfolio loans, new construction and 5+ unit multifamily, with a minimum loan of $75,000. Its Tennessee page positions it as a hard-money alternative.
Best fit: Tennessee residential investment property and small multifamily — a strong option there, and the wrong one for commercial assets.
| Commercial bridge (institutional) | Hard money / private | Conventional permanent | |
|---|---|---|---|
| Rate | Index + spread; below hard money | Roughly 8%–14% (one national lender publishes 7.99%–11.99%) | Lowest of the three |
| Points | 1–2 typical | 2–4 common | 0–1 |
| Term | 12–36 months | 6 months–2 years | 5–25 years |
| Typical size | $5M–$30M | $75K–$2M | $1M+ |
| Sizing basis | Loan-to-cost on transitional assets | Loan-to-value, 60%–70% | 65%–75% LTV |
| Best fit | Hospitality, lease-up, commercial CRE | Residential investment | Stabilized assets |
On hospitality, expect brand, franchise agreement term, RevPAR trend and PIP scope to be examined alongside standard metrics. On Memphis single-tenant industrial, expect lease term and tenant credit to matter as much as occupancy — because the exit depends on a narrow buyer and tenant pool.
AVANA underwrites from its own balance sheet with Oaktree-backed bridge capital, which changes three things for a Tennessee borrower.
The mid-market is the target rather than the leftover — a $2–10 million request is the centre of AVANA’s range at exactly the moment Tennessee’s largest bank has grown well past it. Second, hospitality is a core competency rather than a capped exception, which is the difference that matters most in Nashville. Third, there is no footprint: Chattanooga, Jackson, Clarksville and the Tri-Cities get the same credit process as Nashville, and out-of-state sponsors are routine.
Loan sizes run $5 million to $30 million. See our national guide to the best commercial bridge loan lenders and the bridge loan product page.
Nashville metro (including Franklin and Murfreesboro). The deepest construction pipeline in the state and one of the strongest hotel markets in the Southeast, plus healthcare-headquarters and entertainment-driven office and mixed-use. Hospitality PIP and lease-up bridge dominate.
Memphis. A global logistics hub generating large-footprint, frequently single-tenant industrial. Lower basis than Nashville, with property specificity as the recurring question.
Knoxville. University, healthcare and manufacturing demand with a genuinely local lender bench and strong construction relationships.
Chattanooga. Manufacturing, logistics and a revitalised urban core at a lower basis, with growing out-of-state investor interest and a modest local lender pool.
Tri-Cities (Kingsport, Johnson City, Bristol). Healthcare and manufacturing demand at the state’s lowest basis, served by few institutions — the clearest case for a nationwide lender.
Tennessee’s two dominant bridge scenarios have distinct exits.
Hotel PIP. Completion is the easy part; the ramp is the risk. Post-renovation stabilisation to a higher RevPAR typically takes longer than the construction itself, and a permanent lender will want to see it. A twelve-month bridge on a nine-month PIP leaves three months of ramp — which is not enough. Build to 24–36 months.
Industrial lease-up. Refinance once leased, but check the take-out’s lease-term requirement first. A short lease to a young tenant may clear your bridge lender and fail your permanent lender.
Refinance into SBA 504. For owner-operated hotels and owner-occupied commercial property, bridge-to-504 is a genuine route, since SBA 504 financing offers long fixed-rate amortisation at roughly 10% equity. Slower — start early.
The Tennessee failure mode is a hospitality bridge sized to the renovation budget and the renovation timeline, with nothing left for the ramp. Read our guide to bridge-to-permanent refinancing and negotiate extension options.
The best bridge loan lenders in Tennessee sort by asset type. The state’s short-term lending market is capable and mostly residential. Unitas Funding and Ternus serve Tennessee investors directly, Lima One and Easy Street Capital bring national scale to residential investment property, and Capital Fund 1 offers real speed up to $10 million with a genuine commercial product. If you are buying and renovating houses, these are the right lenders.
The gap is the middle, and it widened this year. Nashville hotels facing brand-mandated PIPs, newly delivered space waiting on tenants, Memphis single-tenant industrial, and mid-market commercial requests that no longer command attention at the state’s largest institution — those need a commercial lender whose range centres on the mid-market, whose deepest asset class is hotels, and who has no footprint to stop at. That is where AVANA Capital lends: commercial bridge from $5 million to $30 million, backed by a joint venture with Oaktree Capital, across Tennessee and all 50 states, on 23+ years and $1.7 billion in closed loans.
Explore more market insights